Insurance Tips

Insurance review: seven life events that should prompt a policy check
CHICAGO — – November 13, 2026 -- If you started working remotely, the mileage estimate on your auto policy may no longer match how much you drive, according to a HelloNation article.

The piece, "Life Changes That Should Trigger an Insurance Review," features Jose Gomez, an insurance expert in Chicago, Illinois. Its argument is that a policy is not a set-it-and-forget-it product and should be checked when your circumstances change.

By our count, the article names seven kinds of trigger:
Is Bundling Home and Auto Insurance Really Cheaper?

Goodyear, Arizona – November 10, 2026 -- A multi-policy discount for bundling home and auto insurance can sometimes reach double-digit percentages, but it does not guarantee a lower bill, according to a HelloNation article featuring Allstate Insurance expert Edward Vasquez.

The discount applies to each policy's base rate

Because the discount is applied to each policy's base rate, a bundle can still cost more than separate coverage if one policy is priced above average. Auto insurance is often the more expensive one, and the discount may not fully offset that gap.

The two products are priced differently. Home premiums reflect property value, construction details and local risks, while auto premiums reflect driving history, vehicle type and usage. When an insurer combines them, it reassesses the overall risk profile, which can push total costs up or down.

Why a $15,000 Roof Repair May Bring an $8,000 Insurance Check

Kalispell – November 06, 2026 -- A covered roof loss with $15,000 in estimated repairs can produce an initial home insurance payment of just $8,000, depending on depreciation and the policy's deductible. A HelloNation article featuring Kalispell, Montana, insurance expert Peggy Schneider breaks down how that gap arises.

Depreciation cuts the value insurers assign to aging property

Property loses value through age, use, and wear, and insurers may weigh an item's age, condition, and expected useful life. This matters most when a policy pays actual cash value, which generally reflects replacement cost minus the loss in value over time. A single homeowners policy may apply different valuation methods to the dwelling, the roof, and household belongings.

Frost Damage Costs Hit €3.6M in Early 2026 for R+V Customers

Wiesbaden – November 05, 2026 -- Frost damage to residential buildings cost German insurer R+V 3.6 million euros in the first three months of 2026. That is six times the 600,000 euros recorded for all of 2025.

Hamburg's 25 centimeters of snow came with a hefty bill

Severe frost and heavy snowfall shaped the start of 2026. The heavy snow in northern Germany was especially unusual: in Hamburg, 25 centimeters of snow created near-alpine conditions. Conny Flörcks of R+V says that several days below freezing often lead to expensive damage to residential buildings.

Frozen water has enormous force. When it bursts water pipes and heating pipes, the building can suffer major water damage and costly repairs. The damage often only becomes visible once the ice thaws and water spreads inside the walls, Flörcks explains.

How Much Life Insurance Do You Really Need? Amarillo Experts Weigh In

Amarillo, Texas – October 05, 2026 -- Amarillo families trying to figure out how much life insurance to buy now have a clearer formula to follow, according to new guidance published by HelloNation. The report breaks down coverage decisions into income replacement, outstanding debts, and long-term household expenses.

A common starting point is five to ten times annual salary

The guidance recommends calculating a baseline coverage amount at five to ten times the primary earner's yearly income. That figure, however, is meant as a starting point rather than a fixed rule, since debts, family size, and future costs can push the right number higher or lower.

Insurance Agent Shares How to Avoid Overpaying for Coverage

Broomfield – October 05, 2026 -- Insurance Agent Rick Hernandez of Broomfield, CO, outlines how policyholders can avoid overpaying for coverage by balancing coverage limits, deductibles, and personal risk tolerance, according to a new HelloNation article.

Coverage limits must match actual asset value, not guesswork.

The article explains that selecting insurance starts with identifying what needs protection, such as a home or vehicle. Coverage limits set too low leave gaps in protection, while limits set too high raise costs without adding meaningful benefit. Individuals with higher-value assets typically need higher coverage limits to stay adequately protected.

Win a Real-Life Street Fighter Car and $25,400 Cash

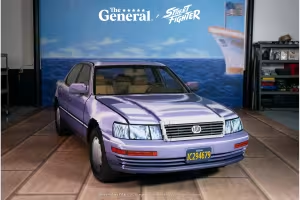
Los Angeles – October 04, 2026 -- The General Insurance has launched a nationwide sweepstakes offering one winner a fully restored, drivable replica of the iconic Street Fighter car plus a cash prize of $25,400.69. Entries are open now through November 18, 2026.

The build debuted live at ComplexCon in Los Angeles

The vehicle, unveiled at the pop culture convention, recreates the pixelated car players have smashed on screen for decades. The design includes custom pixel-patterned upholstery, new leather seats, upgraded speakers and a coin-slot change holder that doubles as a seat warmer.

Term vs. Whole Life Insurance: How to Pick the Right Policy

Saratoga Springs, N.Y. – October 01, 2026 -- Choosing between term and whole life insurance comes down to coverage length, cost, and whether a policyholder wants lifelong protection, according to a new consumer guide published by HelloNation featuring insights from Saratoga Springs-based insurance professional Steve Cook.

Term policies cover a set number of years tied to specific life stages

Term life insurance protects buyers for a defined period, often chosen to match working years, child-rearing, or a mortgage payoff timeline. If the insured dies while the policy is active, it generally pays the stated death benefit. Because term policies focus on protection rather than building extra value, they typically carry a lower initial cost than permanent alternatives. When the term ends, policyholders may need to renew, convert, or replace coverage if they still need protection.

South Texas Homeowners Face Steep Costs From Percentage-Based Hurricane Deductibles

Harlingen, Texas – October 01, 2026 -- Homeowners in South Texas could owe thousands of dollars out of pocket after a hurricane, depending on how their insurance deductible is calculated. A HelloNation article breaks down why hurricane deductibles differ sharply from standard homeowner policies and what that means for storm recovery budgets.

Percentage-based deductibles can cost far more than fixed dollar amounts

Unlike typical home insurance deductibles, which are set dollar figures, hurricane deductibles in South Texas are often calculated as a percentage of a home's insured value. A common rate is two percent, meaning a home insured for two hundred thousand dollars would carry a four thousand dollar deductible. Coastal properties facing higher storm risk often see even steeper percentages.

Why Your Life Insurance Policy Should Change as You Age

Denver – September 30, 2026 -- Life insurance is not a set-it-and-forget-it purchase, according to a new HelloNation article featuring insights from Denver-based Insurance Expert Jack Sughrue, which argues that coverage should be reviewed and adjusted at every major life stage.

Young adults typically start with low-cost term policies

In early adulthood, before dependents or major debt enter the picture, the article notes that term life insurance is the common choice because it delivers coverage for a fixed period at a lower premium, letting people lock in protection without committing to higher long-term costs.